MoneyGram® Money Transfers App

Screenshots
Details
- Rating
- 51.85K reviews
- Version
- 26.7.21
- Developer
- MGI
Analysis by Norviv
Sending money across borders is rarely just a matter of tapping a button. It usually involves a relative waiting for help, a bill that cannot wait, a different currency, and the need to know exactly who is handling the transfer. I tested MoneyGram® Money Transfers as a finance app with that everyday reality in mind, especially in a household where more than one person may help organize payments. My impression is that it is most useful when you want a familiar money-transfer service in a mobile format, while still requiring careful attention to recipient details, fees, exchange rates, and account access.
The app is developed by MGI and is free to install. Its purpose is international money movement rather than budgeting, investing, or managing a shared household account. That distinction matters. I would recommend it to someone who occasionally sends money abroad and wants a focused transfer tool, but I would not treat it as a replacement for a bank account or a complete family-finance app. Its store rating sits at 4.6 from around 128 thousand ratings, and it has passed 5 million installs, which suggests that many people find the basic service useful.
Using the app when a household shares the responsibility
A realistic example is a household where one person receives a message from a relative overseas asking for help, while another person is available to check the recipient’s details or cover the payment. In that situation, the app can be useful because the transfer task is clearly defined: enter the destination information, review the available delivery choices, and complete the transaction through the MoneyGram service. It is easier than passing around paper forms or trying to coordinate a visit to a physical location.
However, shared use needs boundaries. I would not casually leave a signed-in transfer account open on a family tablet or shared phone. A money-transfer app is not the same as a recipe app or a streaming service. The person who can access it may be able to view sensitive transaction information or begin a payment, so the household should agree on who is responsible for starting transfers and who only reviews the details.
My preferred arrangement is simple: one adult manages the account, while another person checks the recipient’s name, country, and amount before the transfer is submitted. That division reduces the chance of a rushed spelling mistake without turning the process into a confusing group project. It also avoids the common problem of several people assuming that someone else has completed the payment.
The app itself should be viewed as a tool for the account holder, not as a family wallet. I would not expect it to separate personal and household transfers automatically, and I would not use it to maintain a shared record of groceries, rent, subscriptions, and international support payments. For those jobs, a banking app or a dedicated household budget may be more appropriate. MoneyGram’s strength is the transfer itself.
What I check before opening a transfer
The most important preparation happens before I touch the send button. I first confirm the recipient’s legal name exactly as it should appear for the chosen delivery method. A nickname that is perfectly clear in a messaging conversation may not be suitable for a financial transaction. I also confirm the destination country, the amount the recipient needs to receive, and whether the person expects money for immediate pickup or another available delivery route.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
This is one of the less obvious habits that makes the experience smoother: I ask the recipient to send their details in one message and then compare them character by character. I do not copy information from a long conversation where an old address or a previous amount might be mixed in. That small workflow is more valuable than rushing through the app, especially when several family members are discussing the same transfer.
I also separate the amount I want the recipient to receive from the amount I am prepared to pay. Currency conversion and transfer charges can affect the final cost, so I review the complete summary rather than focusing only on the headline amount. If the transfer is for a household emergency, I take a screenshot or write down the confirmation details after completion, without exposing them in a group chat.
That last point is important for shared devices. A confirmation screen can contain information that another person does not need to see. I prefer to keep the record with the person responsible for the transfer and tell the recipient directly that it has been sent. This creates a clear chain of communication and reduces duplicate transfers made because two relatives thought the first attempt had failed.
Setup, account boundaries, and the first transfer
MoneyGram® Money Transfers is available for free and supports devices running Android 8.0 or later. The current version is 26.7.21, so users with older phones should check compatibility before planning to rely on it. Installation is only the beginning, though. The practical setup involves deciding whose account will be used, how login information will be protected, and where transfer confirmations will be stored.
I would avoid creating an account with an email address that several household members use casually. A personal address is easier to keep under one person’s control and makes transaction correspondence less likely to be overlooked. I also would not share passwords through a family group chat. Even in a trusting home, chat histories are copied, backed up, and viewed on more devices than people realize.
For a first transfer, I recommend treating the process as a rehearsal rather than an emergency shortcut. Read each screen carefully, confirm the recipient’s details, and make sure the selected destination matches the person you are helping. If another adult is involved, ask them to review the summary before payment. This is especially useful when the household has more than one relative in the same country or when names are similar.
One practical limitation is that a mobile interface can make a complicated decision feel deceptively quick. The app may bring the transfer steps together neatly, but it cannot remove the consequences of entering the wrong information. I would rather spend an extra minute reviewing the final details than assume that a familiar recipient can be corrected easily afterward.
Another boundary is financial responsibility. The person who owns the payment method should understand the total charge and the delivery expectation. A teenager might help read a message or check a spelling, but I would not place them in charge of a household transfer simply because they are more comfortable with apps. The service is rated for Everyone, yet an age label does not automatically mean that every user should handle real-money decisions without adult supervision.
Coordinating transfers without losing track
Coordination becomes more important when relatives live in different time zones. I like to agree on three points before sending: who is sending, who is receiving, and what the money is intended to cover. The purpose does not need to be entered into the app, but stating it in the family conversation prevents misunderstandings. “This is for the electricity bill” is much clearer than “I sent the usual amount.”
I also keep one simple household note with the transfer date, recipient, purpose, and confirmation reference. I do not store passwords there, and I do not make the note accessible to every person who uses the shared device. This approach helps when someone asks whether a payment was completed, while keeping the app from becoming the only place where the family remembers what happened.
A useful trade-off is speed versus review. If the recipient is waiting urgently, a second person checking the details may feel slow. In my experience, that check is worthwhile when the amount is significant or when the recipient’s name is unfamiliar. For a routine transfer to a well-known person, the account holder may reasonably handle it alone, provided the details have already been confirmed.
I would not use a group chat as the main control system for transfers. Group messages are convenient for discussing needs, but they are poor places for sensitive details and can create conflicting instructions. A better pattern is to discuss the request in the group, move the exact recipient information to a private conversation, and have one clearly identified person complete the payment.
The app is also not the best choice when several household members need simultaneous visibility into a complete financial history. A bank account with authorized users or a shared budgeting system may provide a clearer overview for recurring expenses. MoneyGram is more focused: it helps one person initiate a transfer to another person, rather than giving a family a unified financial dashboard.
Age, trust, and the person receiving the money
The Everyone content rating makes the app broadly suitable from a content perspective, but money transfers deserve a more cautious interpretation. I would be comfortable letting a younger family member observe the process or help compare names, but I would keep payment decisions with an adult who understands the destination, the total cost, and the recipient’s circumstances.
Trust also works in both directions. The sender needs confidence that the recipient is genuine, and the recipient needs confidence that the sender has used the correct details. A request that arrives unexpectedly, pressures someone to act immediately, or asks for unusual secrecy deserves verification outside the message that initiated it. The app can process a transfer, but it cannot determine whether a family request is honest.
This is where the service differs from sending money through a familiar bank contact. A bank transfer may feel more natural for people who already share accounts or send money regularly within the same banking network. MoneyGram can be more practical when the recipient is abroad or when a dedicated remittance service fits the situation better. The right choice depends on the destination, delivery needs, total cost, and the level of trust between the people involved.
I would also explain to a new user that “sent” does not necessarily mean “the recipient has already used the money.” Delivery timing and collection arrangements matter. Before starting, I ask the recipient when and how they expect to receive it, then I communicate the confirmation afterward. That avoids the frustrating assumption that a completed transaction and a completed household purchase are always the same event.
Where it fits among the usual alternatives
Compared with visiting a MoneyGram location, the app is more convenient for people who prefer to organize a transfer from a phone. It is particularly helpful when the sender is already at home with the necessary information and does not want to plan a separate visit. The trade-off is that the sender must be comfortable entering details, reviewing the transaction, and managing the digital record without in-person assistance.
Compared with a bank app, MoneyGram is more specialized around international money transfers. A bank may be better for recurring payments between accounts, salary management, or seeing a full household balance. A dedicated remittance service can make more sense when the recipient is not using the same bank or when the transfer needs to follow a particular international route. I would compare the final recipient amount and total sender cost each time rather than assuming one option is always cheapest.
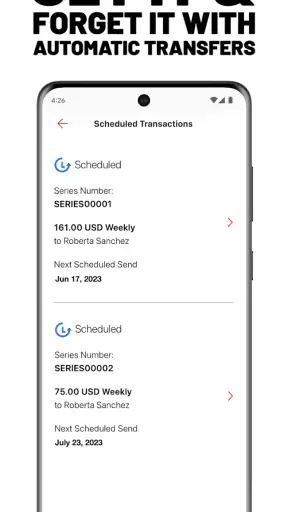
Compared with peer-to-peer payment apps, this service is a better fit when the transfer crosses borders and the recipient’s situation does not match the sender’s domestic payment network. A local payment app may be faster for two people in the same country, especially if both already use it. MoneyGram becomes more compelling when the problem is international reach rather than simply splitting a dinner bill.
One subtle advantage is clarity of purpose. When I use a dedicated transfer app, I am less likely to confuse an international remittance with ordinary spending. That can help a household keep emergency support, regular family assistance, and personal purchases mentally separate. The disadvantage is that it adds another service and another transaction record to manage, which may feel unnecessary for people who already have a convenient bank-to-bank solution.
Who should use it, and who should look elsewhere
I think this app suits people who send money internationally from time to time, households supporting relatives abroad, and users who want to manage a transfer without visiting a physical counter. It is also useful for a family where one person handles the payment while another verifies the details. The free installation lowers the barrier to trying it, although the transfer itself still needs to be reviewed for its complete cost before confirmation.
I would hesitate to recommend it as the main financial app for someone who wants budgeting categories, shared bills, savings goals, or a broad view of household accounts. It is not designed around those needs. I would also suggest comparing alternatives when the recipient and sender already use the same bank, when domestic peer-to-peer payments are sufficient, or when a recurring transfer can be handled more simply through an existing account.
It may not be ideal for someone who dislikes entering personal and recipient information on a phone or who needs a staff member to guide every step. In that case, an in-person option may feel safer and less stressful. Likewise, anyone sending a large or unusually important payment should take time to compare the available methods instead of choosing an app purely because it is familiar.
My strongest practical recommendation is to establish a household rule before the first emergency occurs: one named adult sends, one trusted person may verify, and no one shares login credentials through a common device or group message. That rule is not a feature of the app; it is the habit that makes using a financial app more responsible.
My household verdict
After using MoneyGram® Money Transfers as a focused finance tool, I see its value in the gap between a traditional counter visit and a domestic bank transfer. It gives an international remittance task a clear mobile workflow, and that can make coordination easier when family members are separated by distance. The experience is most convincing when the sender already knows the recipient, has checked the details, and wants a dedicated way to arrange the payment.
Its limitations are equally clear. It does not turn a shared phone into a safe shared account, and it does not replace careful judgment about identity, cost, delivery, or urgency. A household should decide who controls the account, keep confirmations private, and avoid treating the Everyone rating as permission for unsupervised financial use by children.
For occasional international support, I would keep it in consideration, especially when a bank transfer or domestic payment app does not fit the recipient’s situation. For regular household accounting, I would pair it with a bank or budgeting tool rather than expecting it to do everything. My final view is positive but deliberate: the app is most useful when its convenience is matched by disciplined checking and clear account boundaries.
Frequently Asked Questions
01What is the MoneyGram® Money Transfers app used for?
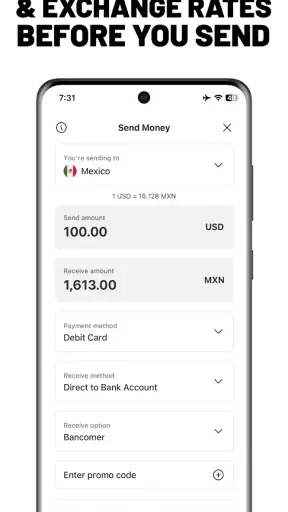
The MoneyGram® Money Transfers app lets you send money internationally or domestically from your mobile device. Depending on the destination and available service, recipients may be able to collect funds in cash at a MoneyGram location, receive them in a bank account, or use other supported delivery methods. The app also helps you estimate fees, review exchange rates, track transfers, and find nearby agent locations.
02How do I send money with the MoneyGram app?
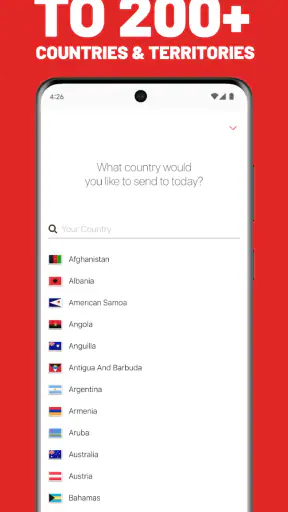
After creating or signing in to your MoneyGram account, enter the recipient’s country, choose the delivery method, provide the required recipient information, and select how you want to pay. Before confirming, carefully check the transfer amount, fees, exchange rate, and estimated delivery time. Requirements and available options can vary by country, and MoneyGram may request identity verification before completing the transaction.
03How much does MoneyGram charge, and what exchange rate will I receive?
MoneyGram fees and exchange rates are not fixed for every transfer. They can depend on the sending and receiving countries, payment method, delivery option, transfer amount, and current promotions. The app normally displays the applicable fee, exchange rate, and total cost before you submit the transfer. Review this final summary carefully, because the recipient may receive a different amount after currency conversion and charges.
04How long does a MoneyGram transfer take, and can I track it?
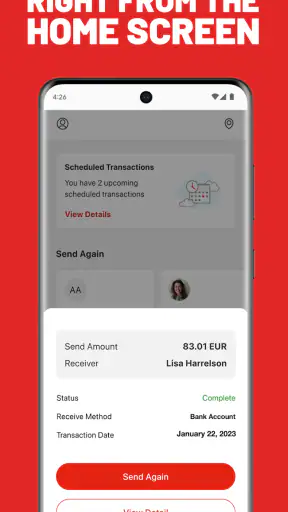
Delivery times vary according to the selected service, destination, payment method, verification requirements, weekends, holidays, and local banking procedures. Some cash-pickup transfers may be available quickly, while bank deposits can take longer. Once a transfer is submitted, you can generally use the app’s tracking feature with the reference number or account details to check its current status and identify possible delays.
05Is the MoneyGram app safe, and what information is required?
MoneyGram uses account security measures and may require personal information, payment details, recipient data, and identity documents to comply with financial regulations. Use only the official app and keep your login credentials, verification codes, and transfer reference number private. Be especially cautious of anyone requesting money through threats, urgent promises, or fake customer-support messages, because completed transfers may be difficult or impossible to reverse.


